

Scenario outcome modeling
TradingView Pine Script Workflow
Trade Outcome Simulator [AGPro Series]
5-Year Access, one-time payment. Manual TradingView activation. TradingView and data fees are separate.
Get Access — $149$149.00
Explore the range of outcomes behind repeating a setup.
Make an outcome scenario's assumptions visible. The simulator combines win rate, fixed payoff, modeled cost and a repetition horizon to show conditional net expectancy and terminal dispersion.
- One focused workflow
- 5-Year Access · one-time
- Manual TradingView activation
Already paid through Whop? Get TradingView access help
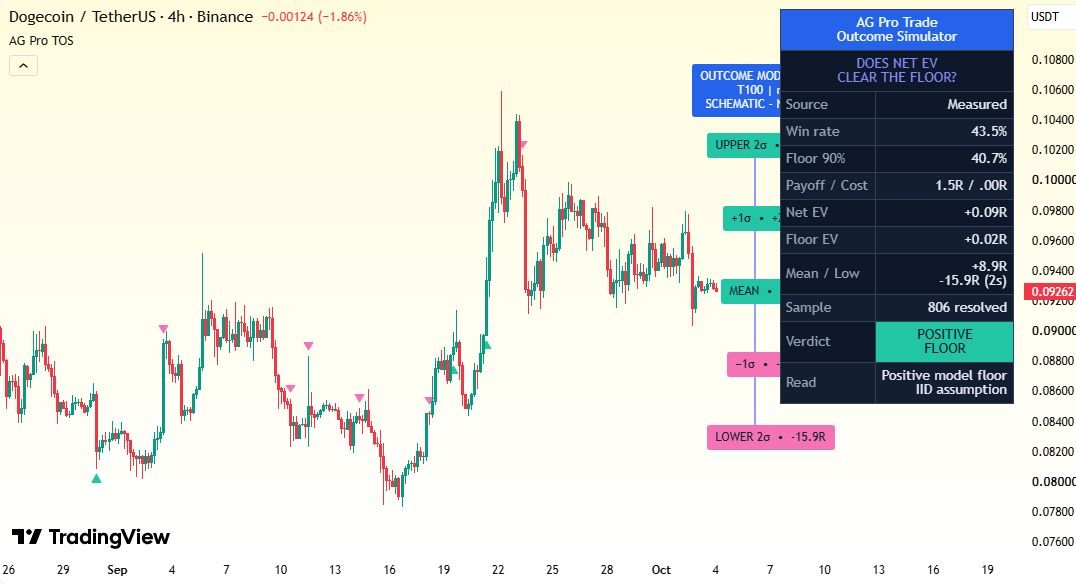
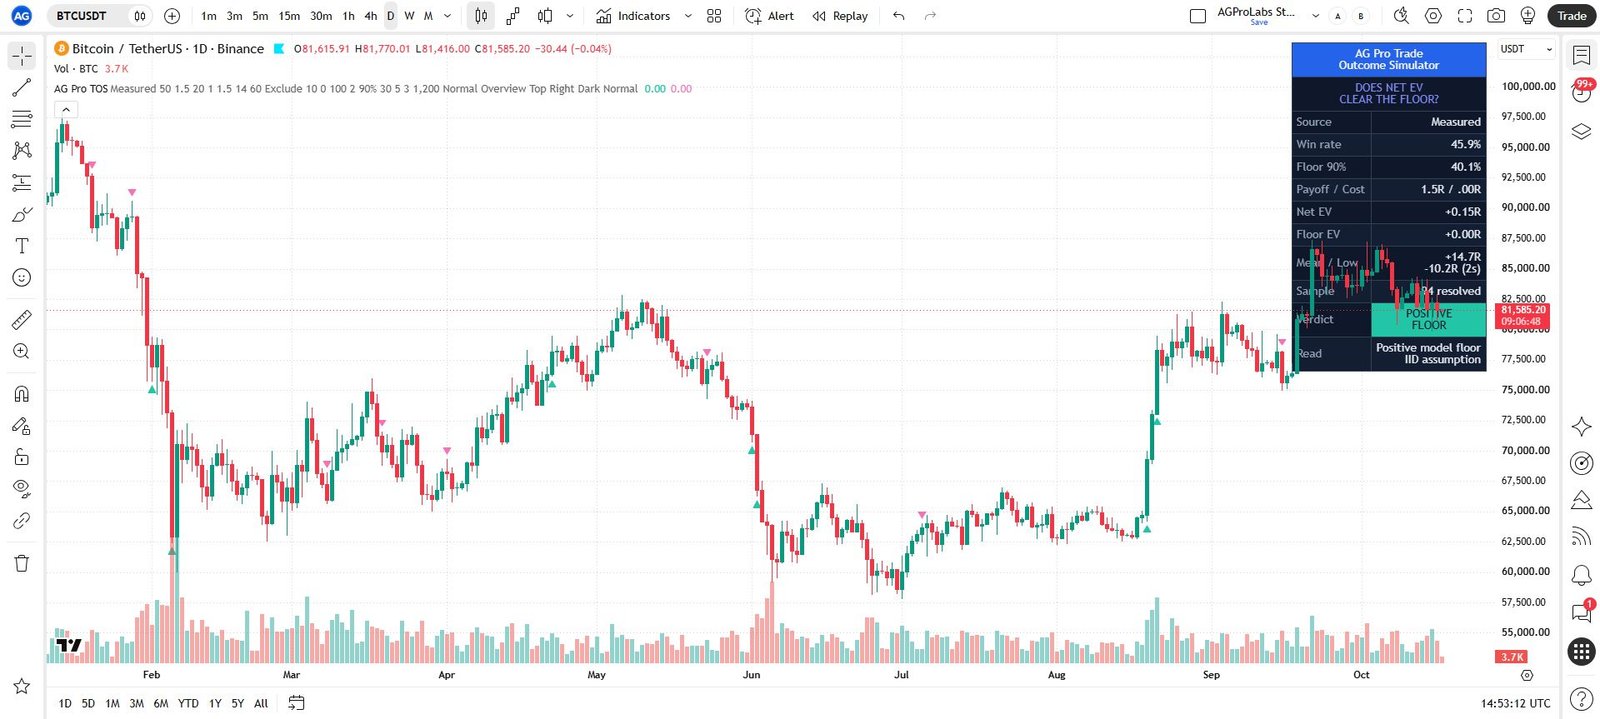
View actual chart & all settings First gallery image: historical TradingView interface. Second image: illustrative cover. Open the gallery to inspect details.
Manual TradingView activation
Submit the exact TradingView username at checkout. Manual review begins after verified payment; access confirmation follows when activation is complete.
One-time payment. No subscription. Available payment methods are shown before order placement.
Need help before purchase? Ask AGProLabs →
Inside Trade Outcome Simulator
Explore the range of outcomes behind repeating a setup.
Trade Outcome Simulator takes a win rate, fixed payoff, modeled round-trip cost, and repetition horizon, then calculates conditional net expectancy and terminal outcome dispersion. Measured mode also evaluates a Wilson lower-bound expectancy floor; Manual mode remains an assumed scenario. The purpose is to make variability and evidence requirements visible without presenting terminal bands as pathwise drawdown or guaranteed best/worst outcomes.
Choose with a clear purpose
What this workflow helps you inspect.
For traders comparing fixed-payoff scenarios and examining how costs, sample evidence and repetition assumptions affect modeled outcomes.
- Compare stated scenarios without confusing manual assumptions with measured chart observations.
- See expected outcome and dispersion together rather than relying on win rate alone.
- Check the measured sample requirement and lower-bound expectancy before interpreting a positive reading.
Read the detailed workflow fit
- For users comparing setup assumptions or trying to understand why a short losing sequence does not, by itself, describe an entire model. Use manual inputs for an explicitly documented scenario, or the built-in measured engine for a chart-based proxy. This is an analytical binomial projection, not random Monte Carlo path generation.
Measured or manual edge assumptions
An outcome projection is only as meaningful as the assumptions feeding it.
Expectancy and variance together
A win rate alone cannot show the balance between wins, losses, and the spread of repeated outcomes.
Series outcome strip
One expected total can conceal the range surrounding that estimate.
See what each layer contributes.
Open a module to explore its purpose, practical interpretation and boundaries. Examples describe a review process; they are not promises of a trading result.
01Measured or manual edge assumptionsAn outcome projection is only as meaningful as the assumptions feeding it.
Measured mode counts confirmed target/stop resolutions from the built-in trigger. Historical OHLC does not reveal an inside-bar order when both levels are touched: the selected Exclude, Stop First or Target First rule applies unless the opening price is already at or beyond an edge. Expired unresolved slots are excluded; wins and losses retain fixed model payoffs rather than gap-adjusted execution returns. Manual mode accepts a chosen win rate and payoff. Keeping these sources explicit makes it possible to distinguish a proxy demonstration from a scenario based on your own records, rather than presenting every input combination as a discovered live edge.
A practical reading
Use manual mode to compare two stated payoff assumptions while leaving the win-rate assumption unchanged.
Keep in view: A measured proxy is not your personal trading record, and optimistic manual inputs can create misleading projections.
02Expectancy and variance togetherA win rate alone cannot show the balance between wins, losses, and the spread of repeated outcomes.
The model computes gross per-outcome R as W multiplied by payoff R, minus the losing fraction, then subtracts the configured fixed cost for net expectancy. The fixed cost shifts the mean but not the two-outcome variance. Comparing both reveals how similar expected values can coexist with different modeled variability.
A practical reading
Review how a larger payoff changes expected R and variability rather than judging it only by the size of a winning trade.
Keep in view: The simplified model does not make real trades independent or keep the actual payoff distribution fixed.
03Series outcome stripOne expected total can conceal the range surrounding that estimate.
Across T repetitions, the conditional net mean scales with T and dispersion with the square root of T. The schematic rail displays upper and lower sigma references and the mean in net R. Its chart position is decorative, not a projection of future price or a list of guaranteed ending outcomes.
A practical reading
Increase the series horizon and inspect how the mean and spread change together under exactly the same edge assumptions.
Keep in view: A positive lower band does not prove that a live process is robust; outcomes outside the displayed sigma reference levels remain possible; the separate Confidence level input applies to the measured Wilson bound.
04Diagnostic quality and measured evidence floorA positive expectancy may still be small relative to the swings assumed by the model.
Measured mode combines net expectancy with a Wilson lower win-rate endpoint and the configured resolved-sample threshold. POSITIVE FLOOR requires positive lower-bound net expectancy and enough resolved observations. Otherwise positive measured expectancy remains provisional; Manual mode identifies positive, breakeven, or negative assumed scenarios.
A practical reading
A positive observed net expectancy can remain provisional when the lower-bound expectancy or resolved-sample threshold is not qualified.
Keep in view: A positive model floor depends on the sample and independence assumptions. Terminal bands do not estimate pathwise drawdown or protect an account from loss.
Understand the controls before changing them.
Explore the main controls and control groups below. Read the current TradingView Inputs and tooltips for the available values; choose a consistent configuration before reviewing its results.
Edge source
Switches between the built-in measured trigger and manually entered assumptions.
When to adjust
When moving from a chart proxy to a documented independent scenario.
Watch for
These are different evidence sources and should be labeled as such.
Manual win rate and payoff R
Define the winning fraction and winning payoff used by the analytical model.
When to adjust
For sensitivity comparisons grounded in plausible records.
Watch for
Do not treat a desirable input as an observed result.
Measured engine controls
Trigger lookback, stop distance, target payoff, and sample controls shape the proxy observations.
When to adjust
When deliberately redefining the measured scenario.
Watch for
A changed engine configuration produces a different sample process.
Series length T
Sets the number of repetitions used for expected total and dispersion calculations.
When to adjust
When examining a different planning horizon.
Watch for
A longer horizon does not ensure the assumed edge remains stable.
Outcome band
Sets the sigma multiple used for upper and lower terminal net-R reference levels.
When to adjust
To inspect sensitivity to the selected sigma multiple; this is separate from the measured Wilson confidence setting.
Watch for
The band is not a worst-case outcome, pathwise drawdown estimate, or hard loss floor.
Complete settings reference
Open complete settings reference
Every setting, explained.
Explore each input, its source default, available choices and practical effect before changing your configuration.
The reference shows defaults in the verified source. A preset or saved chart can retain different input values. Chart captures illustrate the interface and are not a live signal or a performance record.
From first look to a documented observation.
- Choose Measured or Manual and write down what the win rate and payoff actually represent.
- Inspect sample readiness in Measured mode; a Building guard ending is not proof of future validity.
- Read per-trade expectancy before comparing series totals, then inspect both lower and upper outcome bands.
- Compare alternative assumptions with a consistent horizon and confidence setting, keeping correlation, costs, and changing conditions in your separate review.
Answers specific to this workflow.
Does this simulate randomly ordered trades?
No. The source identifies an analytical binomial projection. It calculates distribution measures from inputs rather than generating a random Monte Carlo collection of paths.
Can I use the displayed lower band as my maximum possible loss?
No. It is a moment-based terminal outcome reference under fixed-payoff assumptions. It is not a pathwise drawdown estimate or absolute worst case; clustering, changing edge, and execution differences can produce a materially different experience.
What changes when I increase the series length?
Under unchanged model assumptions, the conditional net mean scales with the number of repetitions, while dispersion scales with its square root. A longer modeled series does not ensure that the assumed edge will persist.
Product overview and access scope
Model repeated trade outcomes from win-rate and payoff inputs. Review conditional net expectancy, variability and terminal outcome references; results depend on the assumptions and do not forecast live returns.
5-Year Access only. Manual activation for one TradingView username after verified payment.
Product-specific chart proof
If you repeated this exact setup a hundred times, what would the results actually look like?
If you repeated this exact setup a hundred times, what would the results actually look like? Trade Outcome Simulator turns that question into a repeatable TradingView review process.

What it organizes
Trade Outcome Simulator uses a setup's win-rate and payoff (R) inputs to model the outcome distribution over repeated trades. It reports net modeled expectancy, variance, standard deviation, and terminal outcome reference bands. Measured mode also evaluates a Wilson lower-bound expectancy floor. These are conditional moment-based estimates, not pathwise drawdown, best/worst outcomes, or forecasts of actual returns.
Analytical and educational use only. No auto-trading, broker execution, financial advice or guaranteed outcome.
Complete product intelligence
Understand the workflow before you activate it.
Purpose, methodology, chart language, operating conditions, controls and limitations are presented below so you can evaluate fit before purchase.
System, Purpose & Difference What the workflow exists to solve, what it produces and why its design differs from generic signal tools.
Core Idea
If you repeated this exact setup a hundred times, what would the results actually look like?
What This Workflow Does
Trade Outcome Simulator uses a setup's win-rate and payoff (R) inputs to model the outcome distribution over repeated trades. It reports net modeled expectancy, variance, standard deviation, and terminal outcome reference bands. Measured mode also evaluates a Wilson lower-bound expectancy floor. These are conditional moment-based estimates, not pathwise drawdown, best/worst outcomes, or forecasts of actual returns.
The win rate and payoff can be measured automatically from a built-in trigger on the current symbol, or entered manually. Win rate, fixed payoff, modeled cost, series length, and the selected sigma multiple determine the net series mean and terminal dispersion references. A diagnostic quality score and the measured confidence-floor verdict summarize the stated model.
Purpose & Design Philosophy
A single trade tells you almost nothing about an edge — outcomes are dominated by variance. Traders abandon good setups after a few losses and over-trust bad ones after a few wins, because they judge edges one trade at a time instead of across the repetition that actually defines them.
Why It Is Different
Most edge tools report a single backward-looking number — a win rate, an average R, a profit factor — and stop there.
This script does NOT stop at a point estimate and does NOT pretend a win rate alone tells you the journey.
Instead, it projects the forward outcome distribution of repeating the setup: not just the expected total, but the standard deviation around it, upper and lower terminal sigma references, and the uncertainty of a conditional repeated-outcome model. It does not estimate the path a trading account will experience.
Methodology & Chart Language How context is processed and how zones, labels, colors, panels and visual states should be read.
Methodology
1. Edge Inputs Win rate (W) and payoff (R) — either measured from a built-in trigger that resolves target-before-stop on the current symbol, or entered manually.
2. Expectancy & Variance Gross per-outcome mean R = W·R − (1−W). The configured round-trip cost is subtracted to obtain net expectancy; a fixed cost shifts the mean, not the two-outcome variance.
3. Series Projection Over T repetitions, the model calculates a net expected total and square-root-of-T dispersion. The selected sigma multiple defines terminal upper and lower reference levels; these are not worst-case losses or pathwise drawdown.
4. Evidence Floor Measured mode uses a Wilson lower win-rate endpoint and the selected resolved-sample threshold before reporting POSITIVE FLOOR. Manual mode reports an assumed scenario, not measured evidence.
How to Read the Chart
- Outcome strip = a schematic net-R rail with upper and lower sigma references and the series mean. Its position beside price is decorative; it does not show price targets.
- Win / loss markers = where the measured engine resolved trades (Measured mode).
- Panel = Overview presents the net model and measured floor; Audit separates resolved, ambiguous/excluded, expired, open-slot, and opening-edge observations. Manual inputs remain labeled assumptions.
Green badges are positive outcomes; pink badges are negative. A positive lower band describes the selected model assumptions; it does not establish that a live trading edge is robust.
Signals, States & Alerts What each visible state represents and when an alert marks a condition that deserves attention.
Signals & States
- POSITIVE FLOOR → measured net lower-bound expectancy is positive and the resolved-sample guard is met under the model
- PROVISIONAL → net measured expectancy is positive but the selected evidence-floor condition is not qualified
- NEGATIVE / BREAKEVEN EXPECTANCY → the net measured mean is non-positive
- POSITIVE / BREAKEVEN / NEGATIVE SCENARIO → Manual mode describes supplied assumptions, not measured evidence
These are confirmed chart/model states, not entry instructions, fills, or future probabilities.
Best Conditions & When to Step Back Where the workflow is most useful, which conditions weaken interpretation and how context changes the reading.
When to Use
- Before adopting a setup type, to judge whether it is worth trading at all.
- To compare conditional net expectancy and terminal variability under explicitly stated assumptions.
- To compare two setups on expectancy-to-variance, not just win rate.
When Not to Use
- As a prediction of any single trade — the projection describes the series, not the next entry.
- With an unrealistic manual win rate or payoff — garbage in, garbage out.
- On too few measured samples. Leaving the Building state only indicates the configured sample requirement; it does not validate future outcomes.
Controls, Interface & Practical Workflow The main inputs, visual controls and a repeatable sequence for using the workflow without losing chart clarity.
Key Inputs
- Edge source → Measured or Manual.
- Manual win rate and payoff R.
- Measured engine → trigger lookback, stop distance, target payoff, samples.
- Series length (T) → how many repetitions to project.
- Outcome band → sigma multiple for terminal net-R reference levels, not a drawdown limit.
Boundaries, Limitations & Risk What the workflow does not do, where its outputs can weaken and the risk boundaries every buyer should understand.
What This Workflow Is Not
- Not a random Monte Carlo simulation — it is an analytical (binomial) projection.
- Not a prediction of any individual trade or of price direction.
- Not financial advice.
- Not an automated trading system, and not a guarantee of any outcome.
Limitations & Transparency
The projection assumes each trade is independent and identically distributed with the given win rate and payoff — real trades cluster, edges drift, and conditions change, so treat the output as a model, not a forecast. Measured win rates depend on the built-in trigger, which is a proxy for your entry, not your exact setup. The terminal bands are moment-based references, not drawdown estimates, absolute best/worst outcomes, or hard loss limits. Read it all as a reasoned estimate to inform judgement.
Risk Disclosure
Trading involves substantial risk. This script is an analytical and educational tool only. It does not provide financial advice or guaranteed outcomes. All trading decisions, and their consequences, remain entirely your own responsibility.
5-Year Access & Delivery The access term, payment-to-activation sequence and the TradingView username required for manual delivery.
5-Year Access & Delivery
- New-purchase access: At least five years of access — 1,827 days from purchase. One-time payment; no automatic renewal.
- One TradingView username: submit the exact username during checkout.
- Manual activation: invite-only access is enabled after payment confirmation.
This is an analytical and educational TradingView workflow. It does not connect to a broker, place trades, manage an account, provide financial advice, or guarantee results. Trading involves risk, and every decision remains the user's responsibility.
Additional Product Intelligence Further product-specific operating notes and context.
Same expectancy, different outcome ranges
In Manual mode, compare two hypothetical setups over 100 outcomes. Set Round-trip cost (R) to 0.05 for both. Start with a 45% win rate and 1.50R payoff, then change the inputs to 75% and 0.50R.
- 45% wins, 1.50R payoff: +7.50R modeled mean, 12.44R terminal standard deviation. The one-standard-deviation references span −4.94R to +19.94R.
- 75% wins, 0.50R payoff: +7.50R modeled mean, 6.50R terminal standard deviation. The one-standard-deviation references span +1.00R to +14.00R.
Both input sets produce the same net expectancy of +0.075R per outcome. The first has a wider spread because its payoff and outcome mix differ. Set Outcome band (σ) to 2 to display the inner ±1σ references on the chart.
These values are calculated from hypothetical inputs. The model assumes independent outcomes with a fixed win rate, payoff and cost. Real trading can produce losses.
Before you buy
Clear access. Clear purpose. No signal-shop promises.
Trade Outcome Simulator is delivered as a TradingView Pine Script workflow for structured analysis and chart review. Access is activated manually for the TradingView username submitted at checkout.
- TradingView accessInvite-only access is enabled after payment confirmation.
- Analysis workflowDesigned for context, structure, risk review and visual discipline.
- Not auto-tradingNo broker connection, no account management and no guaranteed outcome.
Product FAQ
Is this a TradingView Pine Script workflow?
Yes. This product is an invite-only AGPro Series workflow for use inside TradingView.
Does it trade automatically?
No. AGProLabs workflows are analytical tools. They do not connect to brokers, place trades or guarantee outcomes.
How is access activated?
Access is activated manually for the TradingView username submitted during checkout after payment confirmation.
Does access include TradingView or paid market data?
No. This purchase provides invite-only access to the selected AGProLabs workflow. It does not include a TradingView subscription or paid exchange data. Check your TradingView plan, available data, chart resources and alert capabilities for your intended workflow before ordering; contact support if unsure.
Related workflows
-
Risk of Ruin Engine [AGPro Series]
Compare fractional-risk scenarios against a conditional starting-capital loss barrier.
AccessSingle workflow 5-Year Access$149.00 View workflow One 5-Year Access option. View details on the product page. -

Trade Excursion Engine [AGPro Series]
Compare adverse heat and favorable reach in an ATR-normalized historical trigger sample.
AccessSingle workflow 5-Year Access$149.00 View workflow One 5-Year Access option. View details on the product page. -

Risk Reward Execution Matrix [AGPro Series]
Review entry, invalidation and target progression in one chart plan.
AccessSingle workflow 5-Year Access$149.00 View workflow One 5-Year Access option. View details on the product page. -

Trade Management Planner Elite [AGPro Series]
Follow your plan’s entry, risk boundary and next target on the chart.
AccessSingle workflow 5-Year Access$149.00 View workflow One 5-Year Access option. View details on the product page.
Compare other premium products (40)
Open a product to review its methodology, interface and access details.
Confirmation & Playbook
- Adaptive Market Playbook [AGPro Series]
- CME Gap Magnet [AGPro Series]
- Confluence Alert Engine [AGPro Series]
- Crypto Rotation Opportunity Matrix [AGPro Series]
- Crypto Setup Planner [AGPro Series]
- Divergence Reversal Decision Matrix [AGPro Series]
- Dynamic Channels Elite [AGPro Series]
- Edge Confidence Gauge [AGPro Series]
- Edge Consistency Gauge [AGPro Series]
- Expected Move Cone [AGPro Series]
- Market Confirmation Engine [AGPro Series]
- Market Tradability Gate [AGPro Series]
- Rejection Block Execution Planner [AGPro Series]
- Seasonal Edge Clock [AGPro Series]
- Support Resistance Continuation Matrix [AGPro Series]
- Trade Edge Profiler [AGPro Series]
- VWAP Acceptance Execution Matrix [AGPro Series]
Defense & Management
Liquidity & Reclaim
Platform Access
Risk & Execution
SMC & Structure
- Auto Fib Structure Planner [AGPro Series]
- Breaker Block Transition Planner [AGPro Series]
- Harmonic Completion Engine [AGPro Series]
- Institutional Reaction Planner Elite [AGPro Series]
- Structure Failure Recovery Matrix [AGPro Series]
- Trade Conviction Engine [AGPro Series]
- Trendline Retest Execution Matrix [AGPro Series]